

The All-In Podcast hosts recently had a discussion comparing AI to the dot-com bubble. Depending on whom you listened to, the current AI boom resembles 1996, 1998, or perhaps 1999, with some disagreement over how much expansion remained.
Unless you’re in your fifties (like me), most people only “know” those years as history, lived vicariously through other people’s accounts. You can read the stories, learn which companies survived, and study what happened to their businesses and stock prices, but you already know how the story ends. You can’t go back and live the period David Sacks calls “super euphoric and then super miserable.”
I was 25 in 1995 (I know…), living in the Valley, and working at Motorola. I recognize how normal and defensible a bubble can feel before the peak. I sold a company to Sun Microsystems in 2001.


I also know that a technological transformation can be real while the expectations surrounding it become absurd. Because for all the talk about bubbles, AI’s technological expansion, its transformative potential, and speculative excess can coexist.
Calling a bubble and wanting exposure to the expansion can both be right.
What Bubbles Build
Wanting to participate in the expansion is easier to understand when you look at what speculative capital helps finance. In her exceptional treatise “Technological Revolutions, Paradigm Shifts, and Socio-Institutional Change,” Carlota Perez places financial bubbles within a much larger process of technological change, investment, and economic reorganization.
In short, speculative capital can help finance a transformation whose eventual uses and beneficiaries are still unclear. Perez describes technological revolutions as the development of interconnected industries that create markets for one another.
Depending on your perspective on technology, in the current paradigm microprocessors made new computing businesses possible, while advances in software and networking gave people more reasons to buy computers. Falling costs extended their use into the rest of the economy.
Perez calls this a “great surge” of development. During its installation, investment accelerates and infrastructure expands, but financial expectations can outrun the businesses beneath them. The resulting collapse forces those expectations to adjust without undoing everything the investment financed. She calls the period that follows deployment, when the rest of the economy reorganizes around the new infrastructure, much of it now available for a fraction of what its builders paid.
The dot-com bust did this to fiber. Telecom companies laid it across continents and oceans in the late 1990s, many of them betting on WorldCom’s claim that internet traffic was doubling every 100 days. Global Crossing and WorldCom both went bankrupt in 2002, and the fiber stayed in the ground. The glut kept bandwidth cheap for years, which helped YouTube, founded in 2005, afford to stream video for free. As we explored in Artificial Good Enough Intelligence, the technology can continue spreading long after the original investors have lost their money, and the people using it inherit what those investors overpaid for.


That longer history complicates the question of which dot-com year AI currently resembles. Perez dates the information revolution to the Intel microprocessor in 1971. Speaking on Hidden Forces, Nicolas Colin places AI within the maturity of that same computing and network paradigm. He’s describing a transformation measured in decades, while the All-In hosts are trying to locate the peak of a much shorter and more intense investment cycle.
Either way, an established technological system can still produce a rapidly expanding new market.
AI, for example, already has paying customers, substantial revenue, and enormous infrastructure under construction. Despite doubts about their profitability, these are good reasons to take the expansion seriously. Circular financing and “round-tripping” arrangements nevertheless leave open how much demand can sustain itself without the investment helping to fund it. The same boom can build useful businesses while inflating expectations about what they will earn.
Scar Tissue
Those of us who lived through the dot-com boom carry a certain amount of scar tissue. Like the All-In hosts, we keep asking which year we’re in and when it will be time to sell. Experience makes familiar behavior easier to recognize, but it can also leave you constantly preparing to “fight the last war.”
Experience counts for something, but pattern recognition and “institutional memory” can harden into a “handbrake” when useful historical assumptions outlive the conditions that made them useful.


My own expectation is that we still have two or three years of growth before the sector, at least as it’s currently constituted, corrects. We aren’t yet at the fever pitch that usually marks the end, which means plenty of room to participate, and plenty of room to get the timing wrong.
I think of that stage as the “party people” who always show up late to a party and signal that it’s time to leave. Their arrival can be strangely attractive, though. Everyone’s had a few drinks, their faculties are impaired, and more begins to seem inevitable. The conditions telling you to leave are the same ones making it harder to do so. We recognized much of this during the crypto bubble, and still it took a couple of colossal frauds for the party to end.
By the same token, excessive caution has its own cost, too. George Soros’s willingness to “rush in to buy” when he saw a bubble forming illustrates how much money can be made during an expansion that eventually ends badly. Knowing how the story ends actually isn’t as useful as it may seem because what happens before it ends can be substantial.
Experience can help you recognize fragile assumptions and the behavior that sustains them. It cannot tell you whether a particular company will prosper, or what its shares are worth.
Three Judgments
The importance of a technology, the durability of a company’s competitive position, and the return available at its entry price are three separate judgments. Enthusiasm for the first can obscure the other two.
Sun, as always, is a useful example. The demand for servers continued to grow after the dot-com crash, but cheaper Dell hardware running Linux undermined Sun’s position. The market Sun helped create kept expanding as its share of the value moved elsewhere. An investor could have been right about the internet and wrong about the company supplying it.
AI compresses the same problem. On All-In, Sacks described frontier intelligence as a duopoly between OpenAI and Anthropic, with everyone else selling commodity intelligence and competing on price. Chamath Palihapitiya expects closed and open competitors to match a new frontier within three or four months. A lab in that position must keep financing new advances simply to preserve the advantage investors have already paid for.
I think of it as the “dark forest” of AI research: once a company demonstrates that an approach works, competitors have an existence proof. They can reverse-engineer it and build open alternatives, eroding the advantage created by the original discovery. Technical progress can therefore weaken a company’s position even as it enlarges the market.
And then there’s price. Even a critically important company can disappoint investors who overpaid. Cisco sold the routers the internet ran on and, in March 2000, became the most valuable public company in the world, at an enterprise value of 31 times sales. Over the next quarter century, its revenue nearly quintupled and its profits quadrupled. Its share price nevertheless took more than 25 years to regain its dot-com peak. The purchase price had absorbed decades of subsequent growth.
SOURCE: https://www.ft.com/content/b27ae706-6244-4337-81cd-5204bd2b9a00
SOURCE: https://www.ft.com/content/b27ae706-6244-4337-81cd-5204bd2b9a00
Scott McNealy, Sun’s cofounder and chief executive, made the same point in 2002. Sun had traded at $64, roughly ten times revenue. At ten times revenue, a ten-year payback would have required Sun to distribute every dollar of revenue to shareholders for a decade, with nothing spent on employees, production, taxes, or research. His question for the people who bought at that price was reasonable: “What were you thinking?”
Now, the multiples attached to AI are even larger, but so is the growth. Anthropic raised its Series H at approximately 20 times its $47 billion run-rate revenue. Three months earlier, it had been valued at approximately 27 times a $14 billion run rate. The valuation increased two and a half times while the multiple fell.
Growth that fast can make a seemingly extravagant price look reasonable. The investment case depends on how long it lasts, how much capital is required to maintain it, and whether the company retains the value it creates as competitors close the gap.
A bubble call can be correct and still produce terrible investment decisions in both directions. Investors can avoid an expansion they should have participated in, or pay a price that assumes the expansion will accrue indefinitely to one company.
“Do the Work”
For example, Anthropic looked rather different when Anjney Midha was helping it raise money.
He says 21 of the 22 institutional firms he approached to invest in their seed round declined. Working within the machine-learning community, he had read the 2020 scaling-laws paper and understood what it suggested about the relationship between resources and model performance. The research was public, but interpreting it required knowledge that the later revenue figures would make less necessary. By then, of course, the investment on offer had changed. Investors who waited for the revenue got their certainty at the Series H, priced at roughly 20 times run rate. Reading the research early was a way to get the third judgment right as well as the first.

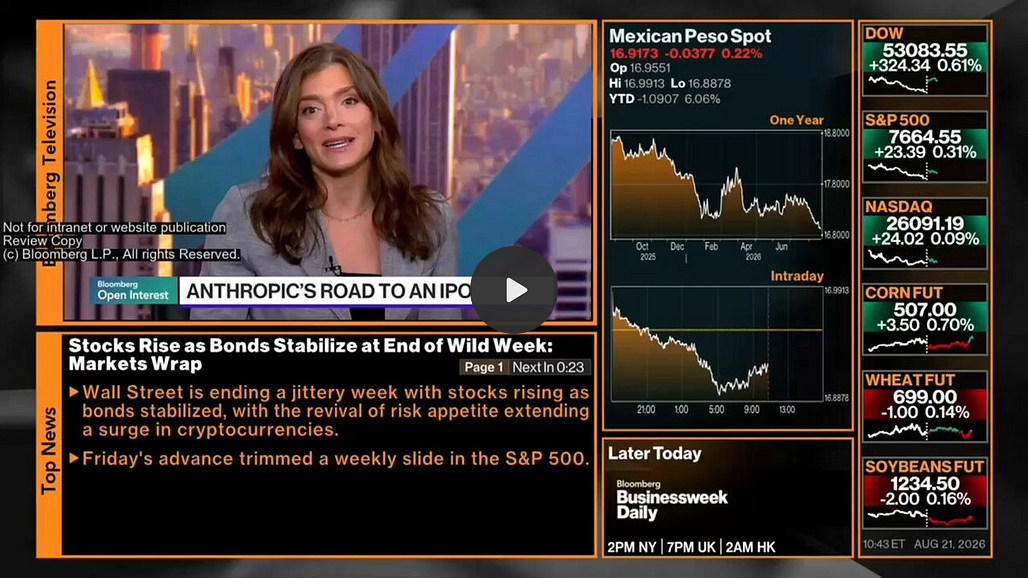
The ability to understand the underlying research and judge its commercial implications becomes particularly valuable during a technological revolution, when the assumptions behind established businesses are changing. Understanding the technology helps you judge whether history or experience is applicable to a current situation.
My Cambridge training was in neural networks at a time when the field was unfashionable enough that the seminars were small. As I wrote recently, I still read papers the way I did twenty-five years ago: slowly, with the suspicion that the interesting claim is in the appendix. Keeping up requires returning to the mathematics and working through what the researchers have actually established.
The scaling-laws papers gave readers who understood them a basis for expecting much more capable models before the products made that prospect obvious. Once ChatGPT arrived, extrapolating further improvement became considerably easier. The more difficult work was thinking through what that progress would do to the economics of the industry, and where it would create opportunities that the prevailing enthusiasm overlooked.
I became interested in what would happen as those capabilities became easier to reproduce and cheaper to deliver. Progress that threatened a model developer’s pricing power could also make AI economical for a much larger population of users. Companies helping those users put the technology to work could benefit from the very improvements making life difficult for the original developers. Understanding that process gave me a thesis to invest against: businesses whose opportunities expand as capable AI becomes cheaper and more widely available.
Below the Frontier
I call that thesis MACHA, or Make AI Cheap Again, and it means investing “below the frontier”: in companies that make capable AI cheaper, more accessible, and useful across a much broader market.
Each of Perez’s surges ran on an input that kept getting cheaper: coal for the steam railways, then steel, then oil, and “cheap microprocessors for the computers and telecom equipment of the current fifth.” Whether AI turns out to be a sixth surge or, as Colin argues, a late expansion of the fifth, it runs on an input of its own, intelligence, and the price of intelligence falls whichever way the bubble argument is settled, so the thesis doesn’t depend on which dot-com year this turns out to be.
If the expansion has another two or three years to run, the labs keep cutting the price of intelligence to win customers, as they are doing now, and as Perez would expect once improvements in production start to matter more than changes to the product. If it breaks, what the boom built gets repriced the way the fiber was. The chips will age faster than fiber did, but the data centers, the grid connections, and the open-weights models will outlast many of the companies that paid for them, and whoever can put them to use will get them at a discount. Businesses built on that input gain customers either way, because each fall in price brings AI within reach of people and companies who couldn’t afford it before.
Stanford’s AI Index found that the cost of matching GPT-3.5’s performance on a widely used language-understanding benchmark fell from $20 to seven cents per million tokens between November 2022 and October 2024, a reduction of more than 280 times. Meanwhile, the frontier continues to advance, despite calls to “pace the frontier” (lol).
Anthropic says Opus 5.5 performs at Fable 5.1’s level on most work while costing roughly 40% less than Opus 5. OpenAI’s new GPT-6 Sol and Luna bring capable reasoning models to lower price points. Sol’s standard input and output token prices are half those of its predecessor, while Luna generates a million output tokens for 50 cents. Even the companies setting the frontier are competing aggressively on how much intelligence a customer gets for a dollar.
For a business building with AI, improvements in capability and cost reinforce one another. A model that can reliably do more work needs less supervision, while cheaper inference makes it economical to use more often. Applications that could not justify their running costs become viable, and companies can afford to experiment with uses that previously made little financial sense. This is how the process improvements Perez describes help a technology spread through the economy.
Prime Intellect’s (Nazaré’s first investment) open reinforcement-learning infrastructure lets companies adapt models to their own work without building the entire optimization system themselves. Vast.ai (Nazaré portfolio company) makes distributed GPU supply available to customers building and running those systems. Their opportunity depends on how effectively they help an expanding population of users turn available capability into something useful.
Three Judgments, Again
The three judgments apply to my own investments too. Importance is the easy one, since it’s the point on which both sides of the bubble argument already agree, and the reason I want exposure at all.
Durability depends on what a company does with its margin, since growing demand gives a supplier no guarantee of keeping its share of the value. Nvidia’s revenue has grown faster than its share price this year, bringing its sales multiple down from roughly 21 in January to 18 in September. Its latest gross margin is still an extraordinary 75%, and at that margin its largest customers have every reason to design their own chips, as Google and Amazon already do. Sun’s margins gave Dell and Linux the same opening after the crash.
Below the frontier, the dark forest mostly helps, because every approach a lab proves out gives open developers an existence proof to copy, which makes the models these companies build on cheaper and better. They get no protection from it, though, because whatever they prove works, competitors can copy too, so their durability has to come from what they do with the savings.
Will Manidis is helpful here. In recounting the importance of the hallowed “Nomad Letters” in his life, he writes: “the thing i remember most from Sleep is his wonderfully strange “robustness ratio,” which measured the amount the customer saved against the value retained by shareholders. value escaping the firm to the consumer, rather than being captured by it, was the metric of a great business. a great business is a lossy one.”


Sleep’s name for the model behind that ratio was “scale economies shared.” A company that passes its savings to customers sells more, the extra volume lowers its costs, and the lower costs make room for the next price cut. It keeps less of each sale than Nvidia does, and the margin it keeps is hard to take away: a rival has to undercut a price already close to cost, and a customer has little reason to replace a supplier that keeps getting cheaper. Below the frontier, that means passing on each fall in the cost of intelligence, so customers use the company for more every time the price drops.
At the stage where I invest, price is the hardest of the three to see. A young company has no revenue multiple to set against Cisco’s 31 or Anthropic’s 20, so its price shows up in the ownership a check buys and in how much more capital the company needs before its market arrives. In a downturn, that second number is the one that hurts, because the next round gets smaller, cheaper, or impossible to raise. Amazon sold $672 million of convertible bonds in February 2000, weeks before the Nasdaq peaked. By Brad Stone’s account the deal would not have closed three weeks later, and that cash carried Amazon through a crash that took almost 90% off its share price within a year. I want to back companies that raise while capital is plentiful, at a price that still works if the next round comes at a lower valuation or not at all.
I may be wrong about having another two or three years, and a correction could arrive sooner. The companies I want to back don’t need me to be right about that, since the input they depend on gets cheaper either way. By the time we can agree on whether this is 1996 or 1999, many of the best investments will already have been made.